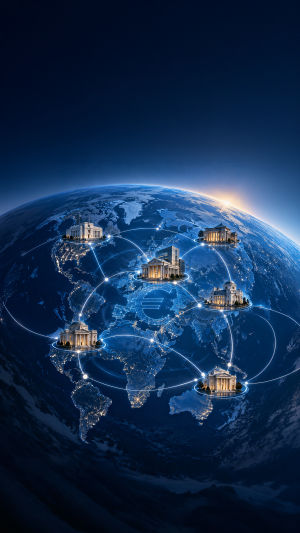
The European Central Bank (ECB) is strengthening arrangements designed to keep euros available to financial institutions outside the euro area during periods of market stress.
The initiative aims to reduce the risk that overseas funding shortages disrupt European financial markets and support the euro’s use in international trade, lending and investment.
<h3>How Currency Safety Nets Work</h3>
International banks and businesses often borrow, lend and settle transactions in currencies other than their domestic currency. During financial turbulence, obtaining a particular currency can become more expensive or difficult, even when the underlying borrower remains financially sound.
Central bank liquidity arrangements can help ease such pressures. Currency swap lines allow two central banks to exchange currencies under agreed terms, with a commitment to reverse the transaction later. Repo facilities provide liquidity in exchange for eligible securities used as collateral.
Both mechanisms can reduce temporary funding shortages, although their structures differ. Their availability depends on the relevant agreements, eligibility requirements and operating conditions. For the euro area, the objective is to limit the risk that funding problems abroad spread to European financial institutions and interfere with the transmission of monetary policy.
<h3>The Role of the EUREP Facility</h3>
An important part of the ECB’s approach is the Eurosystem repo facility for central banks, known as EUREP. The expanded framework provides eligible central banks outside the euro area with access to euro liquidity against high-quality, euro-denominated collateral. Individual facilities can reach up to €50 billion, with transactions generally ranging from overnight to one week and potentially being extended under applicable conditions.
The facility is intended as a temporary safeguard rather than a permanent source of financing. Collateral requirements and pricing help manage financial risks while encouraging central banks to rely on ordinary market funding when conditions permit. Broader access could make euro funding more dependable in markets where the currency is widely used for trade, borrowing and investment.
<h3>Expert Insight</h3>
Piero Cipollone, a member of the ECB’s Executive Board, discussed the preventive role of liquidity arrangements in an official ECB blog post co-authored with Philip Lane and Isabel Schnabel: “the mere existence of a liquidity line pre-empts financial tensions from materialising.”
The principle is that financial safety nets can influence market behaviour even when they are not used. Knowing that temporary funding is available may help financial institutions maintain confidence and reduce pressure to sell assets quickly during periods of stress. Nevertheless, these facilities are safeguards, not substitutes for responsible liquidity management or reliable private-sector financing.
<h3>Supporting the Euro’s International Role</h3>
A currency’s international standing depends partly on whether businesses and financial institutions can use it reliably across borders. The euro is widely used in international trade and financial transactions, but its appeal also depends on the depth of European capital markets and the reliability of payment infrastructure.
Liquidity arrangements address one practical concern: access to euros during periods of financial disruption. When eligible institutions can obtain temporary funding through their central banks, the risk of shortages disrupting euro-denominated transactions may decline. Interest in the expanded EUREP framework also indicates that euro liquidity is relevant beyond the currency union. However, applications and expressions of interest do not necessarily mean that facilities will be used frequently.
<h3>Managing Risks and Maintaining Confidence</h3>
Expanding access to liquidity requires safeguards. Collateral requirements, lending terms and eligibility assessments help limit financial exposure and discourage excessive dependence on central bank funding. The effectiveness of the framework will depend on whether support can be provided when needed without weakening incentives for sound financial management. Monitoring funding conditions and reviewing facility usage can help assess whether the arrangements are fulfilling their intended purpose.
The ECB’s currency safety nets aim to make euro funding more resilient during periods of financial stress. These measures may also strengthen confidence in the euro’s international use. Their long-term value will depend on effective safeguards, reliable financial infrastructure and continued confidence in European monetary institutions.